


On September 18, 2026, The Cato Corporation (NYSE: CATO) announced plans to close approximately 70 additional underperforming retail stores in the second half of fiscal 2026, bringing total closures to around 120 for the year. This move reflects management’s response to deteriorating consumer spending and aims to improve operational efficiency starting in fiscal 2027.
- The company’s Price-to-Sales (P/S) ratio stands at 0.07, significantly below its historical median of approximately 0.3x and well under typical industry levels, signaling that the market is pricing in minimal future growth. Earnings-based valuation metrics like P/E are not applicable due to ongoing losses.
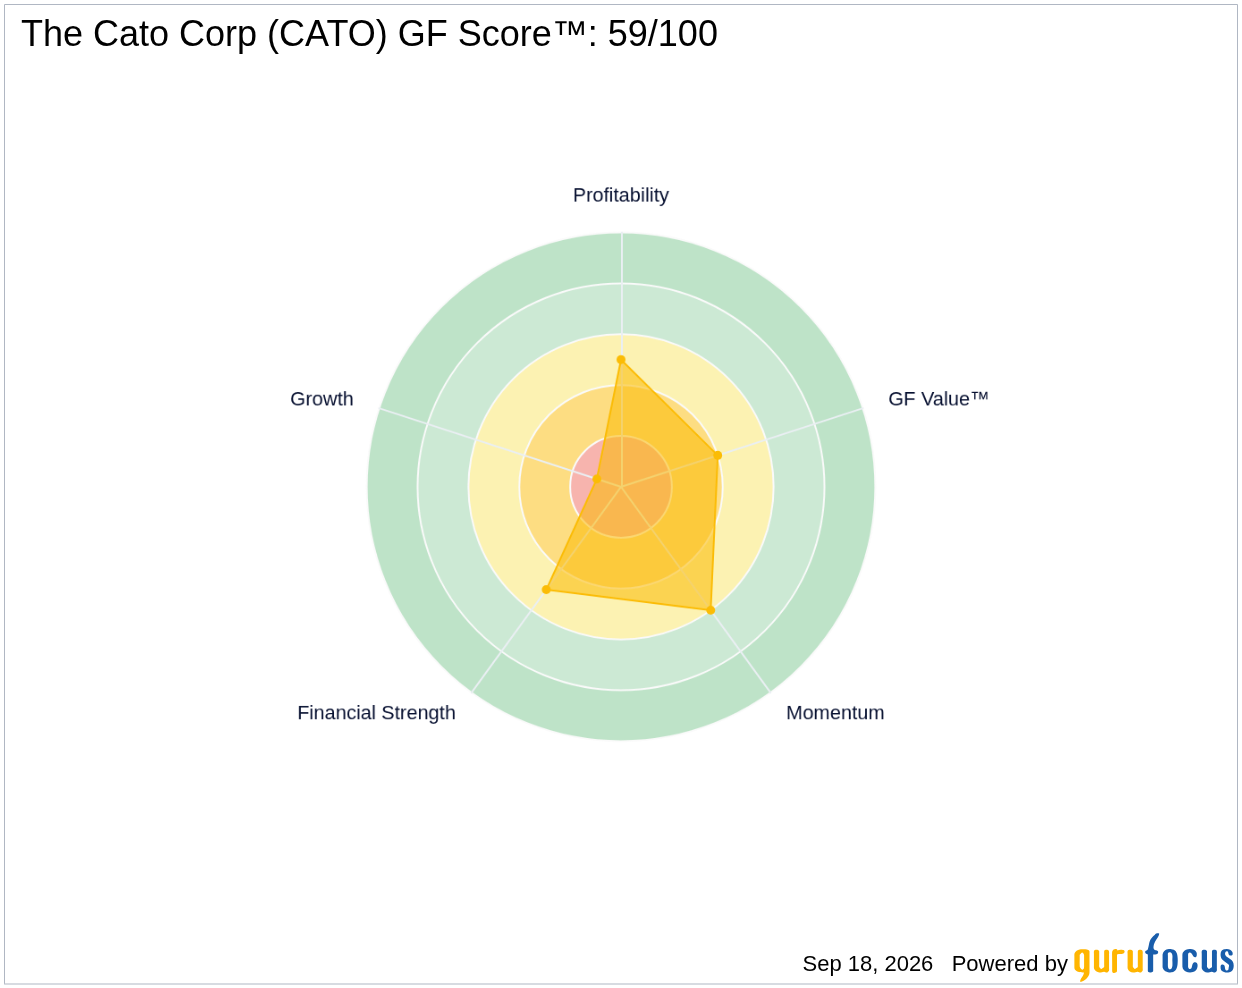
- CATO’s GF Score™ is 59/100, indicating a moderate overall fundamental health with mixed signals across financial strength, profitability, and momentum.
- GuruFocus tracks two premium gurus holding CATO shares, with one adding to their position recently, while insider buying and selling activity remains absent.
What's Behind the News?
The Cato Corporation’s announcement to shutter an additional 70 stores in the latter half of fiscal 2026 is a strategic response to persistent underperformance and a challenging macroeconomic environment marked by declining disposable incomes. The company’s annual store review process evaluates roughly one-third of its locations on sales trends and profitability, historically allowing some underperforming stores a grace period to improve. However, current economic headwinds have led management to accelerate closures, anticipating operational benefits beginning in fiscal 2027. The exit costs are estimated between $1 million and $1.3 million, primarily related to signage removal and inventory returns. Notably, these stores are at the end of their lease terms, so no rental expenses will be incurred beyond 2026.
The Cato Corporation operates as a specialty retailer focusing on women’s fashion apparel and accessories, with brands including Cato, Versona, and It's Fashion. Its retail footprint is concentrated mainly in strip shopping centers across the southeastern, midwestern, and southwestern United States. The company’s market capitalization is approximately $47 million, placing it in the small-cap segment within the Consumer Cyclical sector and the Retail - Cyclical industry.
Is CATO Overvalued on a Price-to-Sales Basis?
CATO’s current Price-to-Sales ratio of 0.07 is markedly below its historical median of roughly 0.3x, reflecting the market’s subdued expectations for the company’s future revenue growth. This low P/S ratio suggests investors are pricing in continued operational challenges and limited top-line expansion. Given CATO’s unprofitable status and negative earnings per share (-$0.28 TTM), traditional earnings-based valuation metrics such as the Price-to-Earnings (P/E) ratio are not meaningful or applicable in assessing its valuation. The company’s negative operating margin (-2.27%) and net margin (-0.87%) further underscore its current lack of profitability.
GuruFocus’ proprietary GF Value™ metric estimates CATO’s intrinsic value at $3.59 per share, compared to the current price of $2.38, implying the stock is approximately 33.7% undervalued. While this valuation signal is directionally significant, it should be interpreted cautiously because GF Value™ relies on historical trading multiples and growth estimates that may be unreliable for a loss-making company facing structural headwinds. For more details, see the GF Value™ definition.
What Does CATO's GF Score™ Tell Us?
The GF Score™ aggregates multiple fundamental factors to provide a snapshot of a company’s overall financial health and investment quality. CATO’s GF Score™ of 59/100 suggests a middling fundamental profile with notable strengths and weaknesses across various dimensions.
| Metric | Rating |
|---|---|
| GF Score™ | 59/100 |
| Financial Strength | 5/10 |
| Profitability | 5/10 |
| Growth | 1/10 |
| Valuation | 4/10 |
| Momentum | 6/10 |
CATO’s moderate Financial Strength and Profitability scores reflect its ongoing operational losses and modest balance sheet metrics, including a current ratio of 1.36 and debt-to-equity ratio of 0.83. The company’s weakest area is Growth, ranked 1/10, consistent with a 3-year revenue decline of -3.4% and a steep 3-year earnings decline of -66.6%. Valuation is also below average, influenced by depressed multiples and market skepticism. Momentum is relatively better at 6/10, indicating some recent price stabilization despite a 52-week price decline of nearly 49%. For a comprehensive view, visit the CATO stock page.
What Are Gurus and Insiders Doing with CATO?
GuruFocus tracks two premium gurus holding CATO shares, with one guru adding to their position in recent quarters and none trimming. This positive guru ownership trend is a notable signal, as such institutional activity is not available from other data providers like Simply Wall St or Morningstar. Insider activity, however, shows no reported buying or selling in the past 3 or 12 months, indicating no recent material insider transactions.
What This Means for Investors
CATO’s extremely low Price-to-Sales ratio signals that the market is pricing in minimal growth prospects amid ongoing losses and store closures. While the GF Value™ metric suggests the stock is significantly undervalued by about 33.7%, this should be viewed as a directional caution rather than a precise valuation target due to the company’s weak earnings and uncertain turnaround prospects. The moderate GF Score™ and mixed financial metrics underscore the risks inherent in the company’s current restructuring phase. However, the presence of committed guru investors adding to their stakes may indicate some confidence in a potential recovery or value opportunity. Investors interested in cyclical retail stocks facing operational challenges may want to monitor CATO’s progress closely. For further analysis and updates, visit the CATO stock page.
Frequently Asked Questions
What is CATO's GF Score™?
CATO’s GF Score™ is 59 out of 100, reflecting a moderate overall fundamental condition with balanced strengths in financial health and momentum but significant weaknesses in growth and valuation.
Is CATO overvalued or undervalued?
Based on its Price-to-Sales ratio of 0.07, well below its historical median, CATO appears undervalued, though earnings-based metrics like P/E are not meaningful due to ongoing losses.
What is CATO's P/E ratio compared to historical?
CATO currently has no meaningful P/E ratio because it is unprofitable, with negative earnings per share and operating margins, highlighting financial challenges rather than valuation concerns.
This stock alert was generated using automated technology and GuruFocus financial data to provide readers with timely and accurate market reporting. This content was reviewed by GuruFocus editorial team prior to publication. Please send any questions or comments about this story to [email protected].

